Why Total Financial Delegation Leaves Even High-Earning Spouses Legally and Personally Exposed
In Belle Burden’s memoir Strangers, one of the most relatable—and quietly devastating—themes is how easily an intelligent, capable person can become completely disconnected from their family’s day-to-day finances.
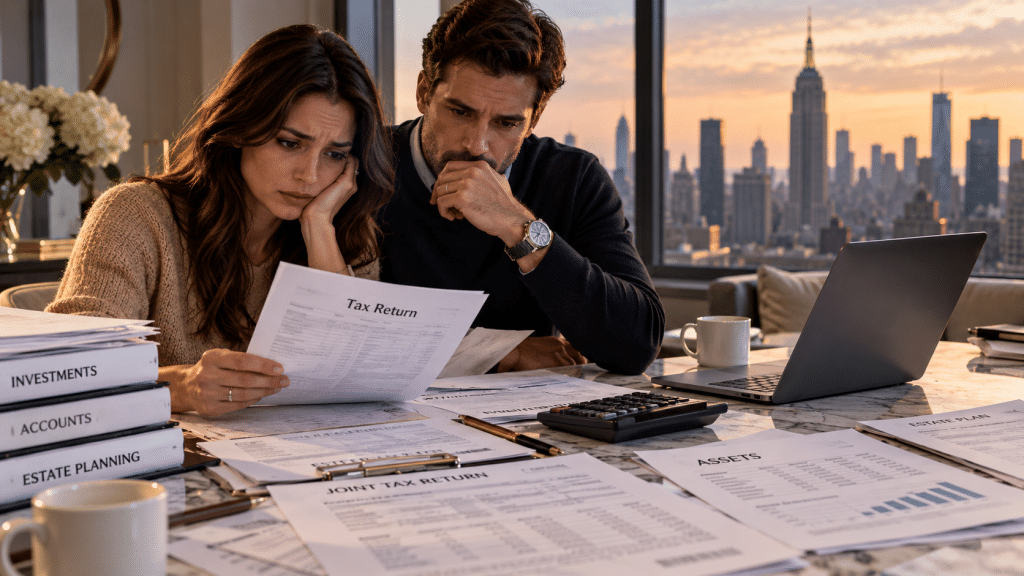
Burden was a trained attorney living in New York City. Yet, as the years went on, a natural division of labor took hold: she focused on their home, children, and personal life, while her spouse managed the investments, bank accounts, and tax returns. When the marriage deteriorated, she found herself not only emotionally adrift, but practically blind to the location, value, and structure of the family’s assets.
In our New York estate planning practice, we see this pattern constantly among high-earning households. One partner—often working in private equity, investment banking, corporate law, or tech—takes over the portfolio, while the other steps back, assuming trust is equivalent to protection.
It isn’t. Total delegation creates immense legal and personal exposure. Even if a marriage remains joyful and lifelong, failing to stay actively involved in family finances leaves the disengaged spouse vulnerable to severe tax liabilities, unexpected incapacity, and administrative paralysis upon death.
The Joint Tax Return Trap: Liability Under IRS and New York Law
Direct Answer (IRC § 6013(d)(3)): When you sign a joint federal and New York State tax return, you become ‘jointly and severally liable’ for 100% of the tax, interest, and fraud penalties due—even if all the income was earned by your spouse and you had no knowledge of errors or omissions.
Signing a joint tax return is not a harmless administrative formality. Under Internal Revenue Code § 6013(d)(3) and New York Tax Law § 651(b)(1), both spouses are individually on the hook for the entire tax bill.
If a high-earning spouse engages in aggressive tax shelters, underreports capital gains, misstates carried interest, or inflates business deductions, the non-involved spouse is equally liable. The IRS and the New York State Department of Taxation and Finance can seize separate bank accounts, garnish personal wages, or place tax liens on individually owned real estate.
The Myth of Easy ‘Innocent Spouse Relief’
Clients often assume the law protects a spouse who didn’t know what was happening. While IRC § 6015 provides for ‘Innocent Spouse Relief,’ qualifying for it in practice is notoriously difficult, particularly for educated professionals:
- Duty of Inquiry: The IRS and courts expect an educated spouse to review the return and ask questions. Turning a blind eye because ‘my spouse handles the money’ does not establish innocent spouse status.
- Lifestyle Disqualification: If the non-earning spouse benefited from the unpaid taxes—through luxury travel, private school tuition, or upscale New York living—the IRS routinely denies equitable relief.
Signing a tax return without reviewing it and understanding its contents is a reckless legal gamble.
Beyond Divorce: The ‘Sudden Single’ Crisis of Incapacity and Death
Financial involvement is not about mistrusting your partner or anticipating divorce. The far more common crisis arises when a loving, faithful spouse is suddenly incapacitated by an accident or illness, or dies unexpectedly.
When the managing spouse is suddenly out of commission, the surviving or caretaking spouse is instantly thrust into managing a complex financial web without a roadmap. In New York, this routinely triggers immediate crises:
- Account Freezes & Liquidity Shortages: If accounts are held in the managing spouse’s sole name, the non-involved spouse cannot access funds to pay mortgages, Manhattan co-op maintenance fees, or medical bills without a valid New York Statutory Short Form Power of Attorney or an emergency court guardianship proceeding (Mental Hygiene Law Article 81).
- Private Equity & Alternative Investments: High-net-worth New York professionals frequently hold capital call commitments, private equity carried interest, or illiquid venture shares. If the surviving spouse does not know when capital calls are due, the family risks costly defaults and forfeitures.
- The Digital Asset Black Hole: With paper statements largely obsolete, modern wealth is trapped behind multi-factor authentication (2FA), password managers, and hardware keys. Under New York’s Revised Uniform Fiduciary Access to Digital Assets Act (EPTL Article 13-A), even an executor cannot easily access digital accounts without explicit legal authorization.
The Family Financial Oversight Framework: From Blind Trust to Active Governance
Maintaining financial visibility does not require splitting household bookkeeping 50/50. It simply requires transparent architecture. High-earning NYC couples should implement the following structure:
| Oversight Domain | High-Risk ‘Blind Trust’ Approach | Healthy Joint Governance Standard |
|---|---|---|
| Tax Returns (Fed & NY) | Blindly signing e-file authorizations (Form 8879) without reviewing returns. | Mandatory joint sit-down with CPA to walk through Schedule 1 deductions, K-1s, and liability before signing. |
| Asset & Debt Balance Sheet | Vague awareness of family net worth; no account numbers, debt terms, or entity lists. | Updated semi-annual master balance sheet listing all liquid accounts, real estate, debts, and trusts. |
| Digital Access & Passwords | Sole spouse controls all logins; accounts locked behind personal phone 2FA. | Shared family digital vault (e.g., 1Password, Bitwarden) storing credentials, policy numbers, and recovery codes. |
| Estate Planning & Powers | Outdated wills from 15 years ago; no signed healthcare proxies or current NY POAs. | Current New York Statutory Short Form POA with explicit digital asset riders and revocable trust. |
Practical Action Steps for the Delegating Spouse
If you have realized that you are financial strangers in your own marriage, you don’t need to provoke a conflict to fix it. Start with these concrete, non-adversarial steps:
- Schedule a Biannual ‘State of the Union’: Set aside one dedicated evening every six months to review total assets, liabilities, debt structures, and estate documents together.
- Meet Directly with the Family Advisors: Attend annual meetings with your CPA, financial advisor, and estate attorney. Both spouses should know the professionals managing family assets by name.
- Establish Emergency Liquidity: Ensure both partners hold independent credit footprints and individual checking/savings accounts funded with 3 to 6 months of living expenses.
- Review and Update New York POAs: Ensure each spouse has designated the other (or a trusted co-agent) under an updated New York Statutory Short Form Power of Attorney, granting legal authority to manage real estate, banks, and tax matters immediately upon incapacity.
Frequently Asked Questions: Financial Oversight and Lessons from Strangers
What financial oversight mistake did Belle Burden make in Strangers?
Belle Burden allowed her husband to completely control their finances, investments, and tax filings, leaving her in the dark about their actual balance sheet. When their marriage disintegrated, this information asymmetry left her legally vulnerable and unable to verify marital assets effectively.
Can you be held legally liable for signing a fraudulent joint tax return your spouse prepared?
Yes. Under IRC § 6013(d)(3) and NY Tax Law § 651, both spouses are jointly and severally liable for all taxes, interest, and fraud penalties on a joint return. Claiming you simply ‘didn’t look at it’ will not protect you from IRS or NY State collection actions.
What happens to family finances if the primary earning spouse becomes incapacitated in New York?
Without a properly executed New York Statutory Short Form Power of Attorney, sole bank and investment accounts are frozen. The healthy spouse cannot sign checks, pay mortgages, or manage investments without undergoing a lengthy, expensive Article 81 guardianship proceeding in New York Supreme Court.
How can a spouse stay financially informed without creating marital conflict?
Frame the discussion around family continuity and estate planning rather than mistrust. Emphasize that in the event of an unexpected medical emergency or sudden death, both spouses must have the knowledge, account access, and legal authority to keep the household running.
What is the difference between innocent spouse relief and separation of liability?
Innocent Spouse Relief (IRC § 6015(b)) relieves you of liability for an understated tax caused by your spouse if you had no knowledge and it is unfair to hold you liable. Separation of Liability (IRC § 6015(c)) allocates the tax deficiency between divorced or separated spouses so each is only responsible for their individual share.
Publishing & SEO/GEO Metadata Specifications
Target Keywords: Belle Burden financial mistakes Strangers, signing joint tax return liability NY, innocent spouse relief DRL, sudden single financial checklist NYC, power of attorney incapacity New York
Meta Title Tag (57 Chars): Financial Blindness Isn’t Romance: Lessons from Strangers
Meta Description (154 Chars): Why is delegating finances dangerous? An NYC estate attorney explains joint tax liability, sudden incapacity, and shared oversight lessons from Belle Burden.
URL Slug: /financial-blindness-lessons-from-belle-burden-strangers/
OpenGraph Title: Financial Blindness Is Not Romance: What Belle Burden’s Memoir Teaches Couples
OpenGraph Description: Trust is not transparency. Why signing joint tax returns blindly and ignoring accounts leaves spouses vulnerable to tax debt and incapacity crises.
LinkedIn Share Copy
Social Copy: In her memoir Strangers, Belle Burden captures a dynamic common in busy, high-earning households: one partner completely delegates the finances to the other.
It rarely starts with bad intentions. It begins as a natural division of labor. But blind trust isn’t transparency—and legally, it is extraordinarily dangerous.
Under federal and New York tax law, signing a joint return makes you 100% liable for fraud and back taxes, even if you never earned a dollar of that income. Worse, if your partner suffers a medical emergency, accounts in their sole name are frozen without updated New York Powers of Attorney.
In our latest guide, we examine:
• Why ‘Innocent Spouse Relief’ is rarely granted to educated professionals
• The ‘Sudden Single’ problem: managing assets during incapacity or death
• A 4-part governance framework for healthy marital financial oversight
Read the full article: [Insert Link]
Disclaimer: This article is for informational purposes only and does not constitute formal legal or tax advice. If you have questions regarding joint tax liabilities, powers of attorney, or family financial governance under New York law, schedule a consultation with an experienced estate planning attorney.