Maximizing the New York State Income Tax Deduction
One of the most compelling advantages of contributing to a NY 529 account for New Yorkers is the state and local tax deduction for state residents. (There is no tax deduction at the federal level for contributions to a 529 account.)
- Single Taxpayers / Married Filing Separately can deduct up to $5,000 in contributions per year from New York State and NYC taxable income.
- Married Couples Filing Jointly can deduct up to $10,000 per year.
With combined state and city income tax rates exceeding 10% for many NY families, that deduction means real money.
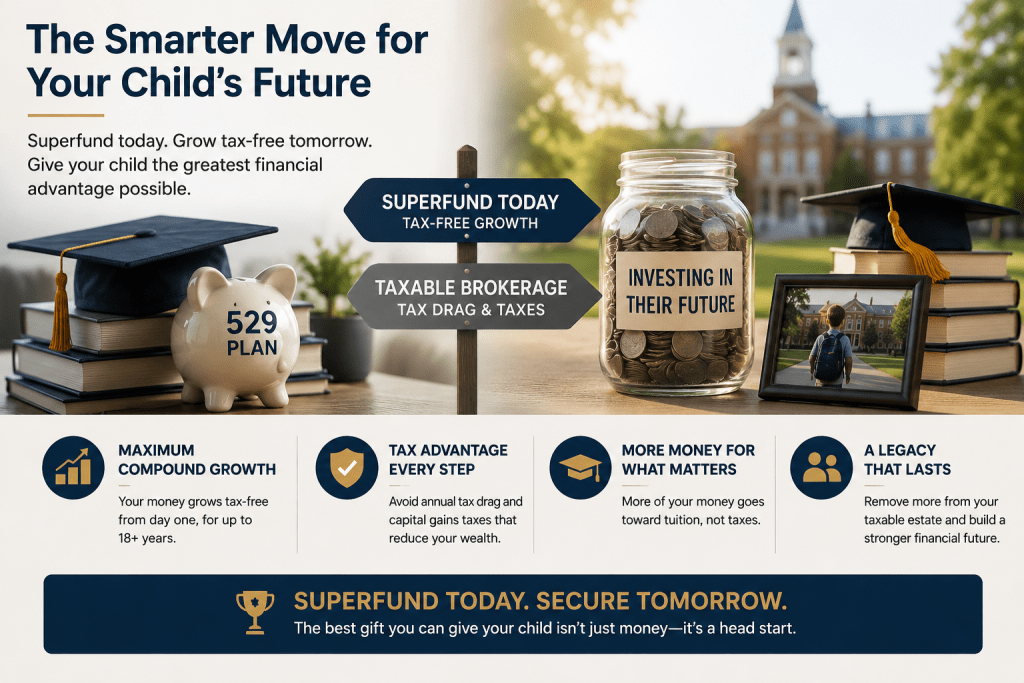
It would seem that maximizing that deduction by making contributions of at least $10,000 each year would be the smartest approach. But, for those families who can afford it, superfunding the account in the first five years can give you an even bigger bang for your buck.
529 “Superfunding” (5-Year Gift Tax Averaging)
Under federal tax law, contributions to a 529 plan are treated as completed gifts to the beneficiary. To accelerate growth, the IRS allows account holders to front-load five years’ worth of annual gift exclusions in a single year—a process known as superfunding.
How Superfunding Works
- Gift Tax Limits: Individual donors can gift up to $19,000 per beneficiary per year ($38,000 for married couples filing jointly) without reporting against their lifetime estate and gift tax exemption.
- The 5-Year Election: Superfunding allows a single parent to contribute up to $95,000 (5 × $19,000) or a married couple to contribute $190,000 (5 × $38,000) per child in a single tax year.
- Form 709 Requirement: You must file IRS Form 709 to elect 5-year gift-tax averaging, spreading the gift evenly across five tax calendar years.
Pros & Cons of Superfunding
Pros
- Maximum Compound Growth: Putting $95,000 to $190,000 to work on day one allows tax-free compounding to operate on a significantly larger base for 18 years.
- Estate Tax Reduction: Instantly removes substantial appreciation and principal from your taxable estate.
- Peace of Mind: College costs are largely or fully pre-funded at birth or early childhood.
Cons
- No NY State Tax Deduction in Following Years: Even if you contribute $190,000 in Year 1, New York State caps your state tax deduction at $10,000 for that tax year. If you were to spread out your contribution over 19 years, you would qualify for a $10,000 tax deduction each year (the equivalent of $18,000).
- No Additional Gifting: You cannot make additional annual exclusion gifts to that same child during the 5-year window without using part of your lifetime exemption.
Superfunding versus Maximizing Deductions: Which Is Better?
Since superfunding an account comes at the expense of the income tax deduction, it may not be clear which strategy is the better approach.
To answer that question, we put the two competing strategies to the test by running a simulation. We asked an LLM (multiple models, actually):
Should you superfund a 529 plan with a $190,000 lump sum on Day 1? Or should you invest that $190,000 in a taxable brokerage account and transfer $10,555 each year into the 529 plan to claim the maximum $10,000 NY State joint tax deduction annually?
We got the answer below.
Spoiler alert: It’s always best to superfund the account.
Here is the comprehensive mathematical and tax breakdown.
NYC Parent Profile & Baseline Assumptions
- Household Income: $500,000 / year (Married Filing Jointly)
- NYS Marginal Tax Rate: 6.85%
- NYC Marginal Tax Rate: 3.876%
- Combined Marginal Rate: 10.726%
- Annual NY 529 Joint Deduction Cap: $10,000
- Annual Tax Savings: $10,000 × 10.726% = $1,072.60 per year
- Time Horizon: 18 Years (Newborn to College)
- Gross Market Growth: 7.0% per year for both accounts
Strategy A: Day 1 Superfund ($190,000 Upfront)
In Strategy A, the parents use the IRS 5-year gift-tax averaging to deposit $190,000 into the NY 529 Direct Plan on Day 1.
Portfolio Mechanics
- 529 Growth: $190,000 grows 100% tax-free at 7.0% per year for 18 years.
- Year 1 Tax Refund: The parents claim the maximum $10,000 joint NY deduction in Year 1, receiving $1,072.60. This refund is invested into a side brokerage account compounding at a net rate of 5.95% (reflecting tax drag).
- Years 2–18: No further 529 contributions are made.
Results at Age 18
- 529 Account Balance (100% Tax-Free): $642,187
- Reinvested Year 1 Tax Refund: $3,025
- Total Combined Net Worth: ~$645,212
Strategy B: Taxable Brokerage + Phased $10,555 Annual 529 Transfers
In Strategy B, the parents invest the full $190,000 into a taxable brokerage account on Day 1. Each year for 18 years, they transfer $10,555.56 from the brokerage account into the 529 plan to max out the $10,000 NY joint tax deduction and reinvest every $1,072.60 tax refund back into the brokerage account.
Portfolio Mechanics & Tax Drag
- Annual Tax Drag (~1.05%): Unlike a 529 plan, the capital in the taxable brokerage account pays annual taxes on dividend yields (~1.8% yield taxed at top rates: 20% federal + 3.8% NIIT + 10.726% NYC = 34.526% total dividend tax rate).
- Realized Capital Gains: Selling $10,555 worth of stock each year to fund the 529 plan triggers realized capital gains taxes.
- Net Growth Rate: The taxable brokerage account grows at an effective net rate of 5.95% per year (7.0% gross − 1.05% tax drag).
Results at Age 18
- 529 Account Balance (100% Tax-Free): ~$383,995
- Remaining Taxable Brokerage Account Balance: ~$201,500
- Reinvested Tax Savings (18 Years of Refunds Compounded): ~$34,750
- Total Combined Net Worth: ~$620,245
| Metric | Strategy A: Day 1 Superfund | Strategy B: Taxable Brokerage + Phased 529 |
|---|---|---|
| Initial Invested Principal | $190,000 in 529 Plan | $190,000 in Taxable Brokerage |
| Cumulative NY Tax Refunds | $1,072.60 (Year 1) | $19,306.80 ($1,072.60 × 18 yrs) |
| 529 Plan Balance (Tax-Free) | $642,187 | $383,995 |
| Taxable Brokerage + Refund Account | $3,025 | $236,250 |
| Total Pre-Tax Wealth at Age 18 | $645,212 | ~$620,245 |
| Tax Status of Final Assets | $642k is 100% TAX-FREE | $236k is TAXABLE (subject to capital gains tax) |
| Net After-Tax Winner | Strategy A wins by ~$25,000+ pre-tax (and ~$40,000+ after liquidation taxes) |
Why Superfunding Beats a Taxable Brokerage Strategy
Even when assuming that 100% of un-contributed funds stay invested in the market from Day 1 and every single tax refund is reinvested, Day 1 superfunding wins due to two structural tax flaws in Strategy B.
1. Annual Tax Drag (0% vs. 1.05% Annual Loss)
In Strategy B, dividend distributions in the brokerage account face combined federal, state, and city tax rates of 34.526%.
In Strategy A, 0% of annual growth is lost to tax drag, allowing the entire $190,000 base to compound unhindered for nearly two decades.
2. The Back-End Liquidation Penalty
When your child attends university at age 18:
Strategy A
You can withdraw all $642,187 tax-free for tuition, room, board, and required equipment.
Strategy B
You have $383,995 in the 529 plan tax-free.
To spend the remaining $236,250 in your taxable brokerage account on college bills, you must liquidate shares and pay 34.526% in long-term capital gains taxes on the growth portion, reducing your actual spendable wealth further.
Strategic Action Plan for High-Earning NYC Families
If You Have Capital Available Today
Superfund immediately.
The tax-free compounding on $190,000 over 18 years easily overcomes losing 17 years of $1,072 state tax deductions.
Execute the Hybrid Strategy
Superfund $190,000 in Year 1.
Once the 5-year gift tax window ends (Year 6), resume making $10,000 annual contributions to capture the NY income tax deduction every year if you think the initial contribution won’t cover all your child’s expenses.
Estate Tax Removal
Superfunding $190,000 instantly removes the $190,000 principal plus all future $450,000+ in market growth from your taxable gross estate for federal and New York State estate tax purposes.