A trust can do more than hold a child’s inheritance: it can set out how that inheritance is managed and distributed. In New York, setting up a trust for a child’s inheritance means preparing a trust document and transferring assets into it. Signing the document before a notary is recommended, although New York law does not strictly require notarization.
A savings account may seem like a straightforward way to set money aside. But the account alone does not explain when or how a child receives the funds. A revocable living trust, by contrast, can let you retain control during your lifetime and revise the plan as circumstances change.
This guide explains what a revocable living trust is, how it compares with a savings account, and the practical steps for creating and notarizing a New York trust for a child’s inheritance. It also explains why funding the trust matters: the written plan can guide only the assets intended to be covered by it.
Key Takeaways
- Understand how a revocable living trust can keep you in control of assets during your lifetime while setting a plan for your child’s inheritance.
- Compare a trust with a savings account by considering how each handles management, access, and distribution instructions.
- Choose a trustee and set clear terms for when and how your child can benefit from trust assets.
- Learn the steps for signing and notarizing a New York trust, then transferring assets into it so the plan can take effect.
What is a revocable living trust?
A living trust is created during your lifetime. A testamentary trust is created through a will and takes effect after death during probate. In New York, a testamentary trust can direct how a child’s inheritance is managed, while a living trust can hold assets during your lifetime.
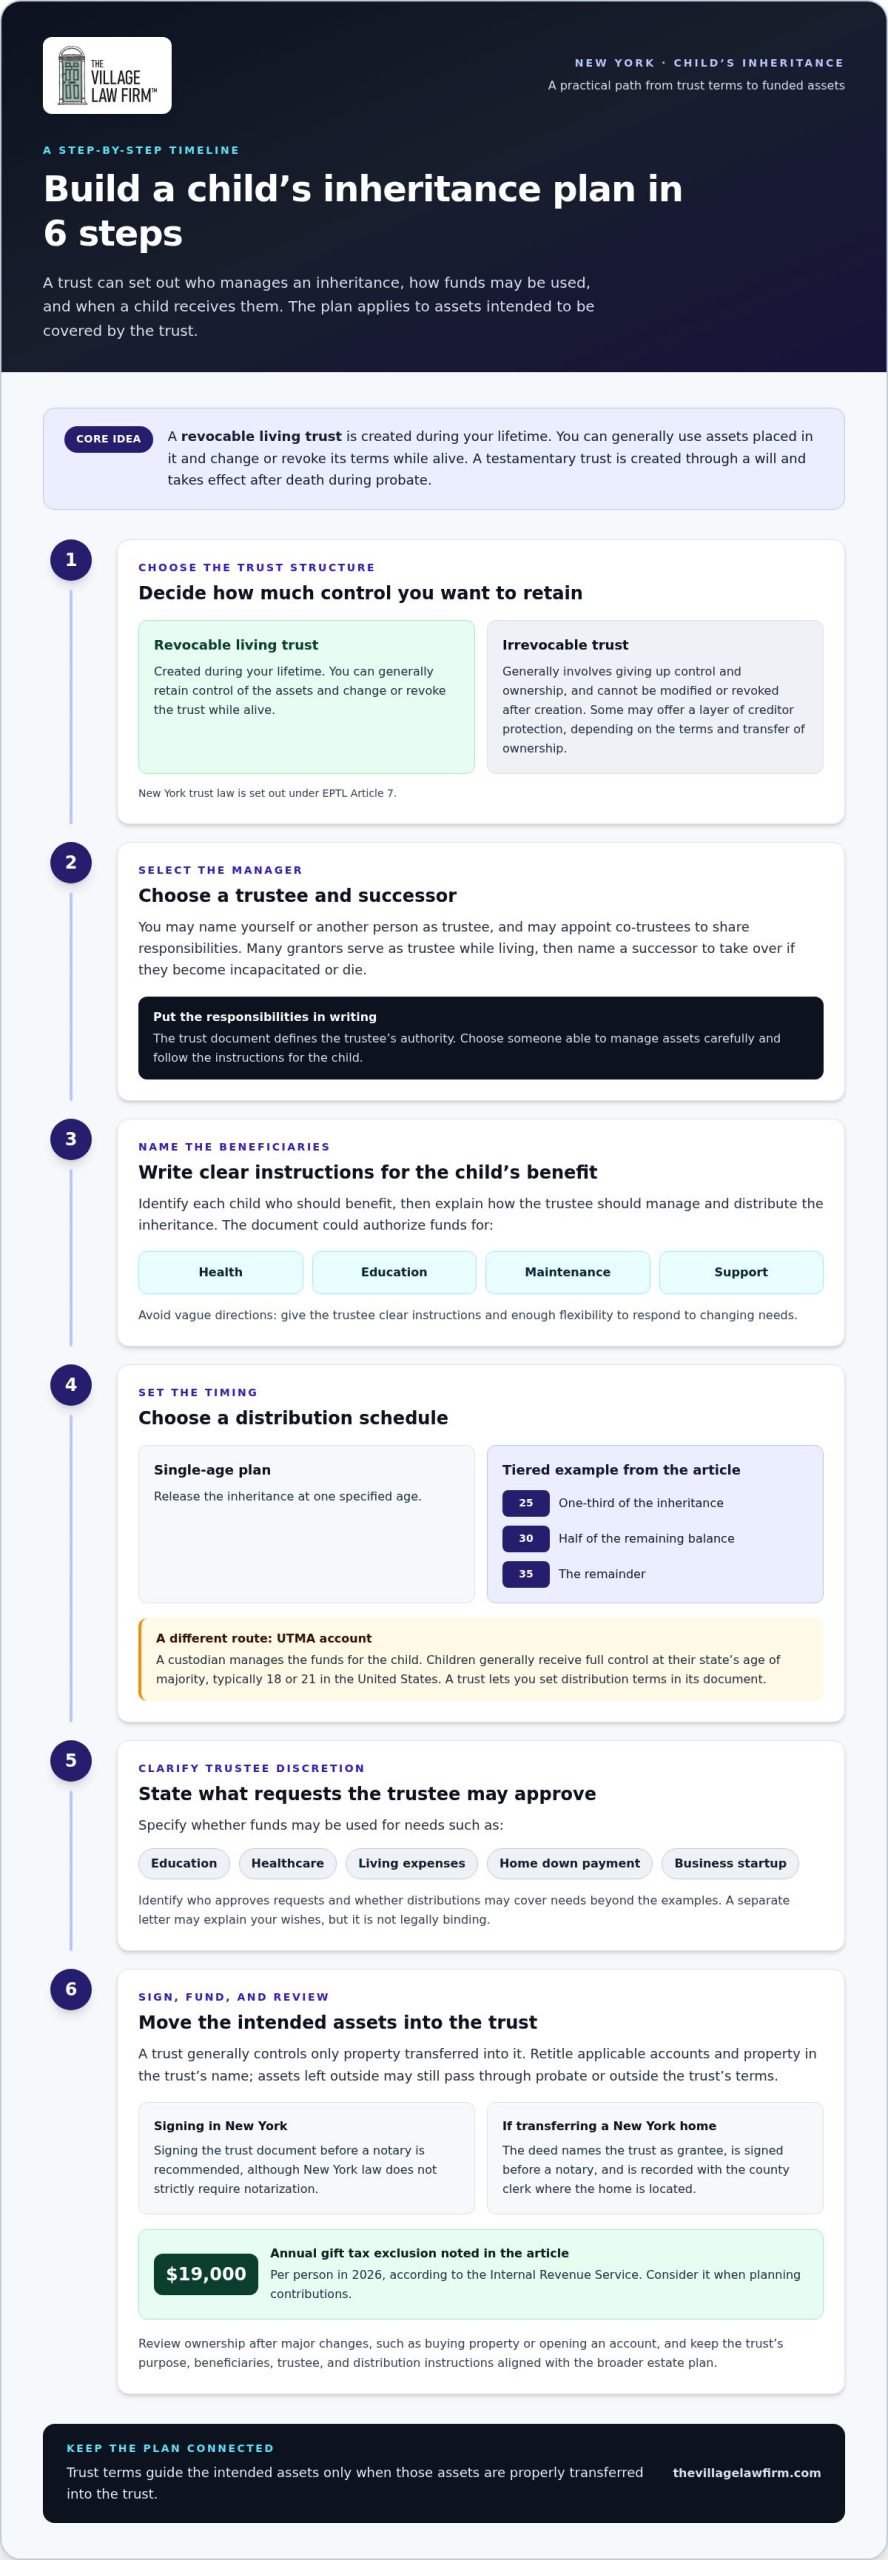
- Choose the type of trust that fits your plan. A revocable living trust lets you retain control of assets and change or revoke the trust during your lifetime. An irrevocable trust generally gives up that control and ownership. New York’s trust law is set out under EPTL Article 7, according to the New York State Senate.
- Set terms for a minor beneficiary. Name a trustee to manage the inheritance and follow the trust document. A testamentary trust can direct the trustee to use funds for a child’s needs and distribute remaining assets at a specified age. It can also avoid the need for an SCPA Article 17 guardian to hold the child’s assets until age 18.
- Define what protection means in your plan. Trust assets can receive some protection under state laws if a beneficiary divorces, but that protection isn’t absolute. An irrevocable trust may offer a layer of protection from creditors or legal judgments, but its terms and the transfer of ownership matter. A revocable trust keeps the grantor in control, so it isn’t interchangeable with an irrevocable trust for asset-protection planning.
- Transfer and retitle the assets you want covered. A trust generally controls only property transferred into it. Retitle applicable accounts and property in the trust’s name; assets left outside may still pass through probate or outside the trust terms. For a New York home, the deed names the trust as grantee, is signed before a notary, and is recorded with the county clerk where the home is located.
- Account for gifts when funding the trust. According to the Internal Revenue Service, the annual gift tax exclusion is $19,000 per person in 2026. Consider that figure when planning contributions, and keep the trust’s purpose, beneficiaries, trustee, and distribution instructions aligned across your estate plan.
Why choose a Trust over a standard savings account?
A trust can do more than hold inheritance: its terms guide who benefits, how funds are managed, and when money is distributed. Use these steps to shape instructions around your child’s needs and your family’s estate planning goals.
-
Name Beneficiaries and Set Distribution Terms
Name each child who should benefit, then specify how the trustee should manage and distribute the inheritance. For example, the document could authorize funds for health, education, maintenance, and support, while delaying full access until a chosen age or milestone. Avoid vague directions: the trustee needs clear instructions and enough flexibility to respond to changing needs.
-
Compare Trusts With UTMA Accounts
Choose between a trust and a UTMA account by considering who controls the funds and when the child gains access. A trust lets you set distribution terms in its document. A UTMA account is managed by a custodian for the child, and children generally receive full control at their state’s age of majority, typically 18 or 21 in the United States.
- Choose a distribution schedule. A single-age plan releases the inheritance at one specified age. A tiered plan can distribute one-third at age 25, half of the remaining balance at age 30, and the remainder at age 35. Set the schedule to match your intentions, rather than defaulting to an immediate full distribution.
- Make conditions and discretion clear. State whether the trustee may fund education, healthcare, living expenses, a home down payment, or a business startup. Identify who is responsible for approving requests and whether funds can be distributed for needs beyond those examples. A separate letter can explain your wishes, but it isn’t legally binding. Align the written terms with your broader estate plan, and discuss your child’s inheritance plan as you refine those instructions.
Revocable living trusts
- Decide whether a revocable trust fits your lifetime plans. A living trust is created during your lifetime and may be revocable or irrevocable. With a revocable living trust, you can generally use the assets placed in it, then change or revoke its terms while alive. For parents whose circumstances may change, this flexibility can help keep an inheritance plan adaptable. An attorney can help align the trust document with your broader estate plan.
- Choose who will manage the trust. You can name yourself as trustee or choose another person, and you can appoint co-trustees to share responsibilities. Many grantors serve as trustee while living, then name a successor trustee to take over if they become incapacitated or die. Choose someone able to manage assets carefully and follow your instructions for the child. The trust document defines the trustee’s authority, so set out responsibilities clearly.
- Coordinate the trust with the assets it should govern. A trust generally controls assets transferred into it, so identify the accounts and property intended for your child and retitle them appropriately. If you sell a house held in a revocable trust, the sale proceeds remain with the trust. Assets left outside it may still pass through probate or outside the trust’s terms. Review ownership after major changes, such as buying property or opening an account.
- Compare revocable and irrevocable terms before signing. An irrevocable trust generally means giving up control and ownership of the assets, and it cannot be modified or revoked after creation. Some irrevocable trusts may offer a layer of creditor protection, but they do not provide the flexibility of a revocable trust. A revocable trust can help keep assets out of probate, yet those assets may still be subject to estate tax. Consider control, intended protection, and distribution needs together with an attorney.
Executing and notarizing a New York trust
To set up a trust for a child’s inheritance in New York, prepare a trust document naming its creator, trustee, beneficiaries, and distribution instructions. Sign the completed revocable living trust before a notary public.
Tax treatment depends partly on the trust type and how it is funded. A revocable living trust can help keep assets out of probate, but its assets may still be subject to estate tax. For 2026, the federal estate tax exemption is $15,000,000 per person and $30,000,000 for married couples.
- Settle the terms before signing. List the child beneficiaries, choose the trustee and successor trustee, and state how the trustee should use or distribute assets. For example, specify whether funds may support education or healthcare, and when the child receives the remaining principal. Clear terms give the trustee practical instructions if you’re unavailable.
- Review the document with an estate planning attorney. Check names, asset descriptions, trustee powers, and distribution conditions for consistency. Confirm that the trust reflects your current wishes and coordinates with your will and other estate planning documents. A signature cannot correct conflicting provisions or unclear directions.
- Sign and notarize the trust document. Sign the final version in front of a notary public, who verifies the signing. Keep the executed document with your important records, and ensure the successor trustee can locate it. Notarization supports clear documentation, even though the trust’s effectiveness also depends on proper terms and funding.
- Fund the trust after execution. Transfer intended assets into the trust and retitle ownership where required. A signed document alone does not place an account or property under the trust’s terms. Review each asset’s ownership and beneficiary designation so the intended inheritance plan works alongside applicable tax considerations.
For help preparing and coordinating your New York trust, work with an estate planning attorney to put the terms and execution steps in order.
The Village Law Firm: Estate Planning
The Village Law Firm helps families plan how assets will be managed and passed on through Estate Planning and Planning for Families with Children. Turn to the firm to coordinate a trust’s beneficiaries, trustee, distribution terms, and funding with the rest of your estate plan. A considered plan can address more than the trust document, including how your child’s inheritance fits with your other wishes and family circumstances.
If a loved one has died and trust or estate matters now need attention, Estate Administration may be relevant. For parents weighing a trust alongside other planning priorities, a conversation can help clarify the decisions that need to be addressed and the next steps. Contact The Village Law Firm to discuss your family’s estate planning, or visit thevillagelawfirm.com.
Take the Next Step Toward a Clear Inheritance Plan
Setting up a New York trust for your child’s inheritance is an opportunity to make your intentions clear before circumstances change. Start by gathering the details that shape your decisions: the assets you want included, the people you trust to help manage them, and the priorities you want reflected in your plan. These choices can give your planning conversation a practical focus.
The Village Law Firm can help you consider how a trust fits into your broader estate planning. The firm also provides Medicaid Planning, which may be relevant if your long-term plans involve both family inheritance and future care considerations. Bring your questions and priorities to the conversation, then work through the decisions with care.
Contact The Village Law Firm to discuss your estate planning. A thoughtful next step can help you move forward with greater clarity and purpose.
Frequently Asked Questions
What is a Trust fund?
A trust fund is property held and managed by a trustee for named beneficiaries under written terms. It may contain cash, investments, or other assets. For example, a parent could place funds in a trust for a child and authorize the trustee to use them for specified needs. The trust’s terms guide how the assets are managed and distributed.
Can I be the Trustee of my child’s Trust?
Yes. A parent can name themselves as trustee if the trust terms appoint them to that role. Consider how you will keep records of trust assets, make decisions under the document, and handle distributions consistently. You can also name a successor trustee to take over if you can no longer manage the trust.
Can I change the rules of the Trust later?
That depends on the type of trust and its terms. A revocable trust can generally be amended or revoked by its creator during their lifetime; an irrevocable trust generally cannot be changed or revoked after creation. If your family circumstances change, such as when a new child joins the family, review whether your documents still reflect your wishes.
Can a Bank or Trust Company Be Trustee?
Yes. A bank or trust company can serve as trustee, as can an individual such as a relative or friend. Consider whether the trustee can manage the responsibilities, communicate with beneficiaries, and follow the trust’s instructions over time. Your choice also determines who makes decisions about requests, recordkeeping, and distributions for your child.
Do I need a lawyer or financial advisor to set up a trust?
An estate planning attorney can help prepare trust terms that address New York requirements and your family’s wishes. A financial advisor may help you consider how the trust fits your assets and investment goals, but that role differs from drafting legal documents. When setting up a trust for a child’s inheritance in New York, clarify who will prepare the legal terms and who will advise on financial decisions.
How much does it cost to set up a trust?
The cost depends on the case, including the trust’s complexity, the assets involved, and whether other estate planning documents need coordination. Legal-service pricing is provided after a quote request. A straightforward arrangement may involve different work from a plan involving several beneficiaries, property, or detailed distribution terms, so compare the scope of work rather than relying on a generic estimate.