What if the state of New York, rather than your own carefully chosen inner circle, decided exactly how and when your children could access their inheritance? Many parents believe that a standard Will provides sufficient protection for their legacy. In reality, leaving assets directly to a minor often leads to a rigid, court-mandated guardianship process that is both emotionally taxing and financially inefficient. You deserve a more elegant solution for your family’s future.
We understand that your primary goal is to create a sanctuary of order. You want to ensure your children are supported without being overwhelmed by a sudden windfall or bogged down by the complexities of the New York Surrogate’s Court. This guide provides a sophisticated roadmap for establishing a trust for minor children New York families rely on to safeguard their wealth. It’s about replacing anxiety with meticulous planning and total clarity.
We will explore the essential steps of selecting a steadfast trustee, the nuances of asset protection, and the specific legal strategies that keep your private financial matters out of the public record. This article outlines how to secure your children’s financial future while ensuring your assets remain protected from mismanagement or creditors. By the end, you’ll have the path forward to provide lasting security for the people who matter most.
Key Takeaways
- Learn why a basic Will often forces your family into the Surrogate’s Court and how to bypass the mandatory $10,000 threshold for court-appointed property guardians.
- Discover the most effective trust for minor children New York parents can use to provide long-term financial stability while avoiding the limitations of UTMA accounts.
- Prepare for the 2026 federal tax sunset and the New York “Estate Tax Cliff” to shield your children’s inheritance from unnecessary tax burdens.
- Master the art of selecting trustees and guardians by understanding why the person best suited to raise your children might not be the right person to manage their money.
- Gain peace of mind with a clear, methodical roadmap that protects your assets from creditors and ensures your children receive their inheritance at the right age.
Why a Basic Will is Often Insufficient for New York Minors
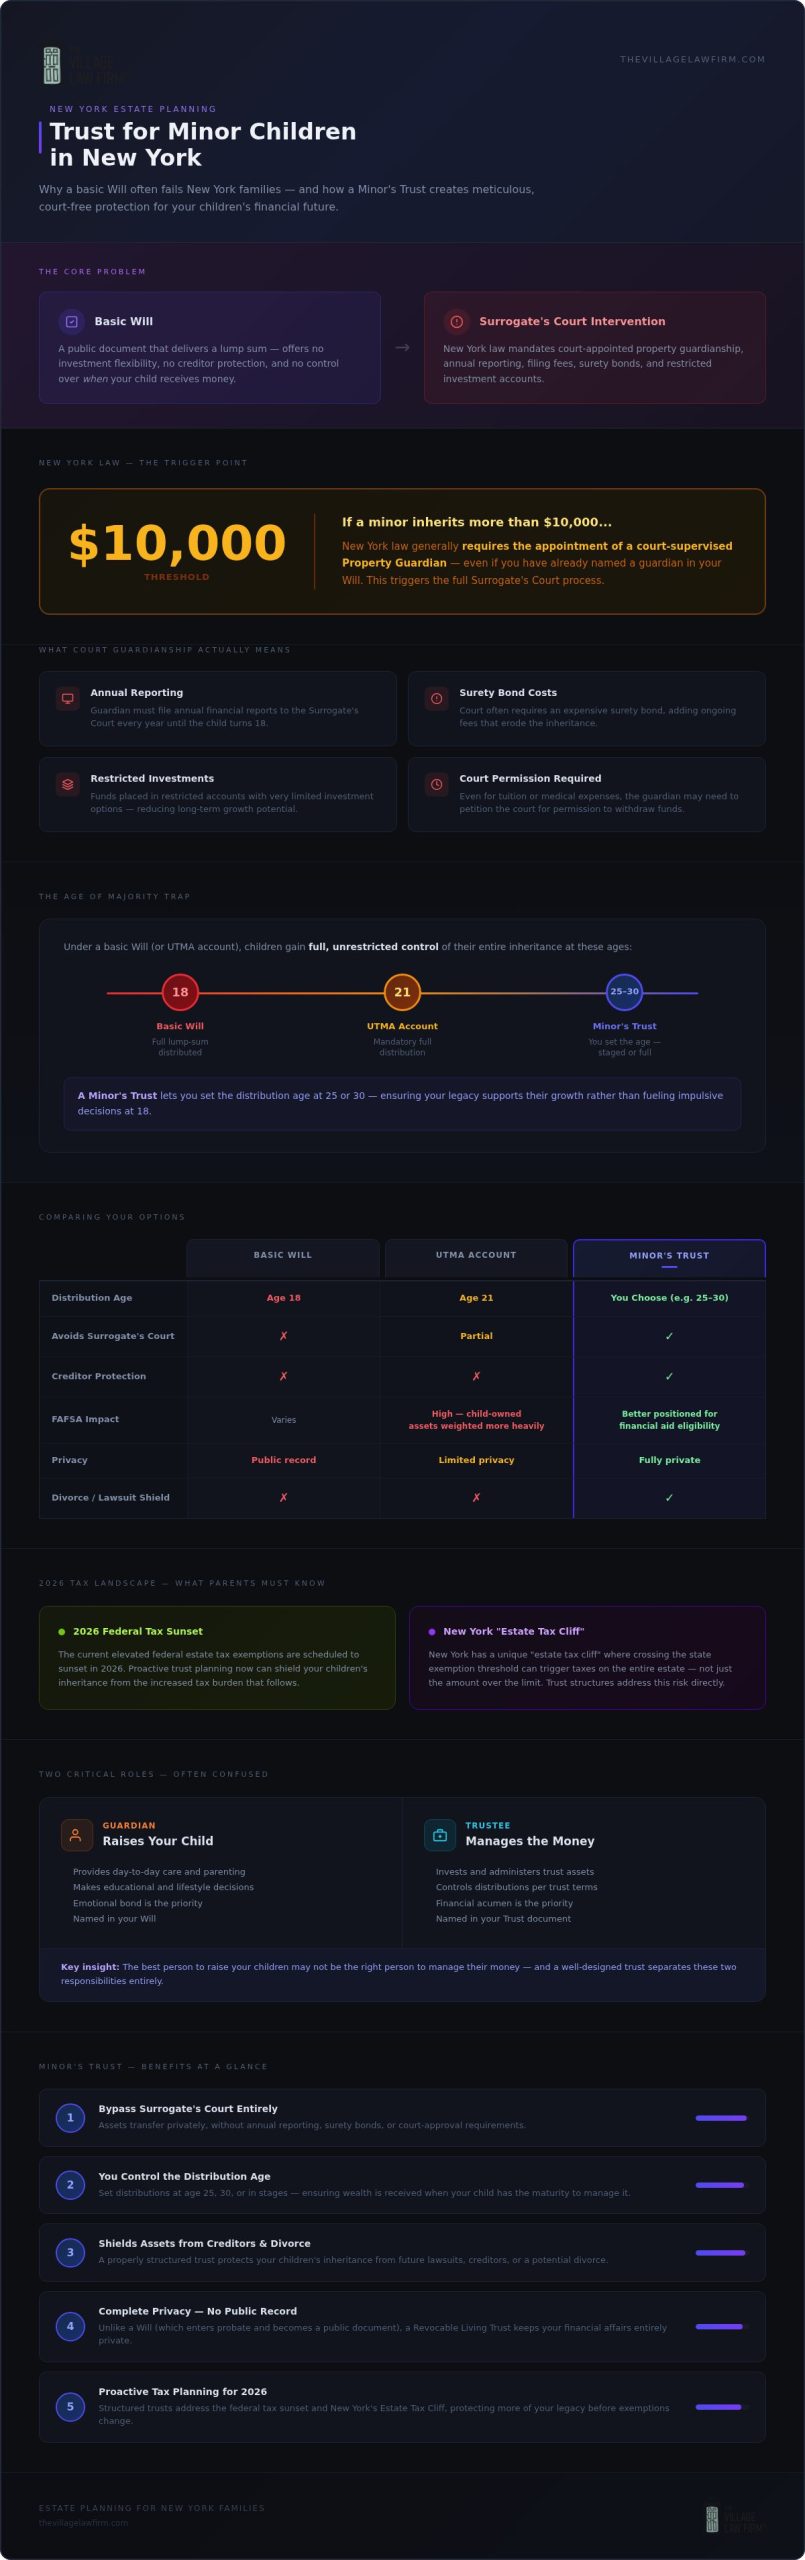
A standard Will is often the first document parents consider when planning for their family’s future. While it’s a vital foundation, relying on a Will alone to transfer assets to young children in New York can create unintended hurdles. New York law is exceptionally protective of minors, but this protection often manifests as rigid bureaucracy. If a minor inherits more than $10,000, the law generally requires the appointment of a property guardian, even if you’ve named a guardian in your Will.
This court intervention isn’t just a formality; it’s a complex legal layer. The Surrogate’s Court oversees these assets with a level of scrutiny that many parents find intrusive. You’ll face hidden costs like annual reporting requirements, filing fees, and the often expensive requirement for a surety bond. These expenses eat away at the inheritance you worked so hard to build. Establishing a trust for minor children New York families can use allows you to bypass this court-supervised chaos entirely.
The Reality of Court-Appointed Property Guardianship
In New York, the “Guardian of the Property” is a specific legal role tasked with managing a child’s assets under court supervision. This often means the money is placed in restricted accounts that offer limited investment options. If the child needs funds for a specific expense, such as tuition or a medical need, the guardian may have to petition the court for permission to withdraw the money. This process is time-consuming and expensive. It’s a far cry from the flexibility of the Uniform Transfers to Minors Act (UTMA) or a private trust, which provides a more seamless transition of wealth.
Asset Protection Beyond the Basics
A Will is essentially a public instruction manual that delivers a lump sum. It offers no protection against the child’s future creditors, lawsuits, or a potential divorce later in life. Perhaps most concerning is the “Age of Majority” trap. Under a basic Will, a child typically gains full control of their inheritance at age 18. Most eighteen-year-olds lack the financial maturity to manage significant wealth. A Minor’s Trust is a legal bridge between childhood and financial maturity. By setting the age of distribution at 25 or 30, you ensure your legacy supports their growth rather than fueling a lifestyle of impulse. A trust for minor children New York residents choose provides the meticulous structure needed to protect assets from mismanagement while ensuring the money is used for its intended purpose.
Comparing Trust Structures: UTMA vs. Revocable Living Trusts
Not all legal vehicles are created equal. Choosing the right mechanism for a trust for minor children New York families depend on requires balancing ease of setup with long-term protection. While some options are simple to initiate, they often lack the nuance required for complex legacies or significant assets. You need a structure that evolves as your children grow, ensuring that your wealth serves as a foundation rather than a burden.
UTMA Accounts: The Simple but Rigid Option
Under the New York Estates, Powers and Trusts Law (EPTL), the Uniform Transfers to Minors Act (UTMA) provides a straightforward way to hold property for a child. It’s often the default choice for modest gifts because it doesn’t require a complex trust document. However, it carries a significant drawback: the mandatory distribution age. In New York, the custodian must usually turn over the entire account to the child at age 21. For high-net-worth families, handing over a large sum to a young adult can be a source of deep anxiety.
There’s also the impact on college planning to consider. Assets held in an UTMA account are legally considered the child’s property. Under the 2026 FAFSA rules, student-owned assets are weighted much more heavily than parental assets, which can significantly reduce eligibility for financial aid. If you’re building a substantial legacy, you’ll likely find that your family has outgrown the UTMA’s narrow framework.
The Power of the Standalone Living Trust
A Revocable Living Trust is the gold standard for NYC professionals who value privacy and meticulous control. Unlike a Will, which must pass through the public probate process, a Living Trust operates privately and remains outside the reach of the Surrogate’s Court. You can dictate specific milestones for distributions; perhaps your child receives one third at age 25, half of the remainder at 30, and the balance at 35. This staggered approach encourages financial responsibility and protects the principal during their most formative years.
For families with international ties, these trusts are particularly effective at integrating cross-border assets into a single, cohesive plan. You can ensure your global legacy remains protected according to IRS estate and gift tax guidelines while avoiding the chaos of conflicting jurisdictions. It’s a sophisticated way to maintain order across a complex life. If you’re ready to move beyond basic templates, planning for families with children requires a partner who understands these nuanced legal distinctions. We focus on creating a sanctuary of order that reflects your specific values and long-term goals.
You might also consider a Testamentary Trust, which is a trust for minor children New York parents create within their Will. While it provides more control than an UTMA, it only comes into existence after your Will is probated. This means your family still faces the delays and public nature of the court system. For those seeking the most seamless and private transition, the Living Trust remains the superior choice for modern New York legacies.
Funding Your Child’s Trust in the 2026 Tax Landscape
Establishing a trust for minor children New York families rely on is only the first step; the second is ensuring it’s properly funded within a shifting tax environment. As we approach 2026, the sunset of the Tax Cuts and Jobs Act (TCJA) looms over many estate plans. This change is expected to effectively halve the federal estate tax exemption, meaning more families will find their legacies subject to significant taxation. Strategic funding now can protect your children’s future from being eroded by these upcoming shifts.
Life Insurance as a Primary Funding Vehicle
Life insurance often serves as the most effective anchor for a minor’s trust. It provides immediate liquidity exactly when it’s needed most, ensuring your children are cared for without the need to liquidate family real estate or business interests. However, a common mistake is naming a minor child directly as the beneficiary. This triggers the very court intervention we aim to avoid. By naming the trust as the beneficiary, you ensure the proceeds are managed by your chosen trustee according to your specific instructions. This approach aligns perfectly with a broader strategy for NYC Estate Planning: 2026 Parent’s Guide to Legal Security, where every asset is meticulously positioned for maximum protection.
New York Estate Tax Considerations for 2026
New York’s estate tax system features a unique and often punishing “cliff.” If an estate exceeds the exemption amount by even a small margin, the state taxes the entire estate from dollar one. While the NY exemption is adjusted annually for inflation, staying below this threshold is critical for preserving wealth. A trust for minor children New York parents implement can “soak up” assets through lifetime gifting or strategic beneficiary designations. You can learn more about managing these specific risks in our guide to the New York Estate Tax Exemption 2026 & 2026.
Beyond insurance, you can fund the trust with real estate or brokerage accounts. To maximize tax efficiency, many parents utilize “Crummey” powers. This provision allows you to make annual gifts to the trust that qualify for the federal gift tax exclusion. By following IRS estate and gift tax guidelines, you can incrementally build your child’s inheritance without exhausting your lifetime exemption. It’s a patient, methodical way to build a sanctuary of financial security for the next generation.
The NYC Parent’s Dilemma: Choosing Trustees and Guardians
One of the most profound decisions you’ll make involves selecting the individuals who will step into your shoes. In a high-stakes environment like New York, this choice is often complicated by the distinct needs of your children’s daily care versus their long-term financial security. It’s vital to recognize that the person best suited to provide a nurturing home might not be the one best equipped to manage a complex investment portfolio. You’re looking for two different skill sets: the heart of a caregiver and the mind of a steward.
For many NYC families, proximity and lifestyle values are paramount. If your chosen guardian lives across the globe, the transition for your children could be jarring. Conversely, for expat families, you might consider appointing non-US citizen guardians. This “International Factor” requires meticulous legal drafting to ensure your wishes are enforceable across borders. A trust for minor children New York parents create must account for these geographical realities to maintain stability. Successor planning is equally critical; you must name at least one backup to ensure the stewardship of your legacy never falters if your first choice is unavailable.
Selecting the Trustee (The Financial Steward)
The trustee acts as the financial engine of your child’s future. While a family member might offer emotional connection, a professional trustee provides impartial expertise and a shield against family conflicts. They don’t get distracted by family dynamics. Under New York law, trustees have strict fiduciary duties. They must manage assets with the highest level of care and loyalty. To add an extra layer of security, you can appoint a Trust Protector. This individual has the authority to oversee the trustee’s actions and even replace them if necessary, ensuring the trust always serves your child’s best interests. This oversight provides a sanctuary of order for your assets.
Appointing the Legal Guardian (The Caregiver)
While the trustee manages the money, the legal guardian provides the home. You must formalize this appointment in your Will to prevent the Surrogate’s Court from making this deeply personal decision for you. For busy professionals who travel frequently, establishing both temporary and permanent guardianship is a sophisticated way to ensure your children are never left in legal limbo. It’s about total protection.
Clear documentation is the only way to avoid painful family disputes during a time of crisis. Understanding How to Appoint a Legal Guardian for Children in New York is a fundamental component of your broader security strategy. It’s about creating a comprehensive shield that covers both the heart and the bank account. If you’re ready to secure your family’s future with a partner who values precision and empathy, planning for families with children allows you to start this journey with confidence and clarity.
The Village Law Firm Approach: Sophisticated Planning for Modern Legacies
At The Village Law Firm, we believe that high-end estate planning should be a sanctuary of order, not a source of further stress. Our “White-Glove” philosophy is centered on removing the friction from legal processes. We understand that your time is your most valuable asset. That’s why we take a methodical approach to establishing a trust for minor children New York professionals can trust to perform when it matters most. We replace the inherent unpredictability of the future with a structured, transparent roadmap tailored to your family’s unique architecture.
Our firm specializes in moving families from a state of “Chaos” to “Calm.” This transition involves more than just drafting documents; it’s about building a partnership that prioritizes long-term security. We also incorporate Medicaid-conscious strategies into our planning. This ensures that your wealth remains protected for multiple generations, shielding your children’s inheritance from potential long-term care costs or administrative mismanagement. We act as your steady urban guide through these complex legacy decisions, providing a shield against future uncertainty.
Customized Trusts for Global New Yorkers
New York is a global hub, and many of our clients manage lives that span multiple continents. We possess deep expertise in handling foreign assets and navigating the needs of multinational beneficiaries. When establishing a trust for minor children New York families with global ties require, we ensure total compliance with both US and foreign inheritance laws. This global perspective is further detailed in our 2026 Guide: International Estate Planning in New York. We bridge the gap between jurisdictions to ensure your legacy remains seamless and secure, regardless of where your assets are located.
Starting Your Journey Toward Security
Your path toward peace of mind begins with a focused strategy session. During this initial consultation, we listen to your concerns and analyze your family’s specific needs. We don’t believe in transactional law; we believe in ongoing support. As your children grow and your financial landscape evolves, we work alongside you to update your plan. This ensures your legal shield remains robust and relevant. If you are ready to replace anxiety with a sense of meticulous protection, we invite you to schedule a strategy session with The Village Law Firm. Let us help you secure the future you have worked so hard to build.
Building Your Family’s Sanctuary of Order
Securing your legacy in a city as dynamic as New York requires more than just a simple document; it demands a strategic roadmap. You’ve seen how a trust for minor children New York families rely on provides the necessary shield against the rigid bureaucracy of the Surrogate’s Court and the upcoming 2026 tax shifts. By moving beyond a basic Will, you ensure your children receive their inheritance with the maturity and protection they deserve. It’s about ensuring your hard-earned assets stay within the family rather than being consumed by court fees or administrative mismanagement.
Our boutique firm specializes in providing white-glove service to busy professionals who value precision, discretion, and a proven track record in avoiding probate chaos. Whether you’re managing local real estate or complex international interests, we help you navigate these high-stakes decisions with empathy and clarity. Secure your children’s future with a sophisticated New York estate plan. Contact The Village Law Firm today. We’re ready to help you replace uncertainty with a lasting sense of peace and security for the next generation.
Frequently Asked Questions
What is the best type of trust for a minor child in New York?
A Revocable Living Trust is often considered the gold standard for its flexibility and privacy. Unlike UTMA accounts that generally mandate distribution at age 21, a Living Trust allows parents to set specific milestones, such as ages 25 or 30. This ensures the inheritance supports long-term goals rather than immediate impulses. It also keeps your family out of the public Surrogate’s Court probate process, maintaining a sanctuary of order for your legacy.
Can a minor child be a beneficiary of a trust in NY?
Yes, a minor can be a beneficiary, but they cannot legally manage property over $10,000 in New York. Without a trust, the court will appoint a property guardian to oversee the assets until the child turns 18. Establishing a trust for minor children New York parents use ensures that a person you choose, rather than a court appointee, manages the inheritance. This protects the assets from rigid court restrictions and unnecessary administrative costs.
Who should I choose as a trustee for my children’s trust?
You should choose someone who possesses both financial literacy and unwavering integrity. While a family member may understand your children’s personal needs, a professional trustee or a trust company offers impartial management and professional expertise. Many parents appoint a family member as a guardian for daily care and a professional or trusted advisor as the trustee for financial oversight. This strategy ensures a balance between emotional support and technical precision.
How much does it cost to set up a trust for a minor in NYC?
The investment for establishing a trust in New York varies based on the complexity of your assets and family dynamics. While we don’t quote fixed prices without a strategy session, the cost reflects the level of customization required for high-end estate planning. Most families find that the upfront cost is significantly lower than the long-term expenses of court-supervised guardianship, surety bonding requirements, and the filing fees associated with annual reporting.
What happens if I don’t have a trust and I pass away with minor children?
Your estate will go through the probate process, and assets left to minors will trigger a court-appointed property guardianship. This often means the money is held in restricted accounts until the child turns 18. At that age, they receive the entire balance in a single lump sum. This “Age of Majority” trap often leads to rapid mismanagement and leaves the inheritance vulnerable to creditors or the child’s own financial inexperience.
Can I change the terms of the trust as my children get older?
Yes, if you utilize a Revocable Living Trust, you can update the terms as your family evolves. You might decide to change the distribution ages, swap trustees, or adjust how funds are used for specialized education. This flexibility is vital for a trust for minor children New York families depend on, as it allows your plan to grow alongside your children’s changing needs and maturity levels without requiring court permission.
How does a trust for minors interact with New York estate taxes in 2026?
The 2026 tax landscape features a significant sunset of federal exemptions, making strategic trust funding more critical for NYC professionals. New York also has an “estate tax cliff” where exceeding the exemption by even a small margin can lead to the entire estate being taxed from the first dollar. Trusts can help mitigate this exposure by utilizing annual gifting exclusions and keeping assets out of your taxable estate, preserving more wealth for your children’s future.
Do I need a trust if I already have a life insurance policy?
You absolutely need a trust even if you have a life insurance policy. Life insurance provides the liquidity, but the trust provides the instructions. If you name a minor as a beneficiary, the insurance company cannot pay them directly; the court will intervene to manage the proceeds. By naming your trust as the beneficiary, you ensure the money is managed by your chosen trustee for your child’s benefit according to your exact terms.